

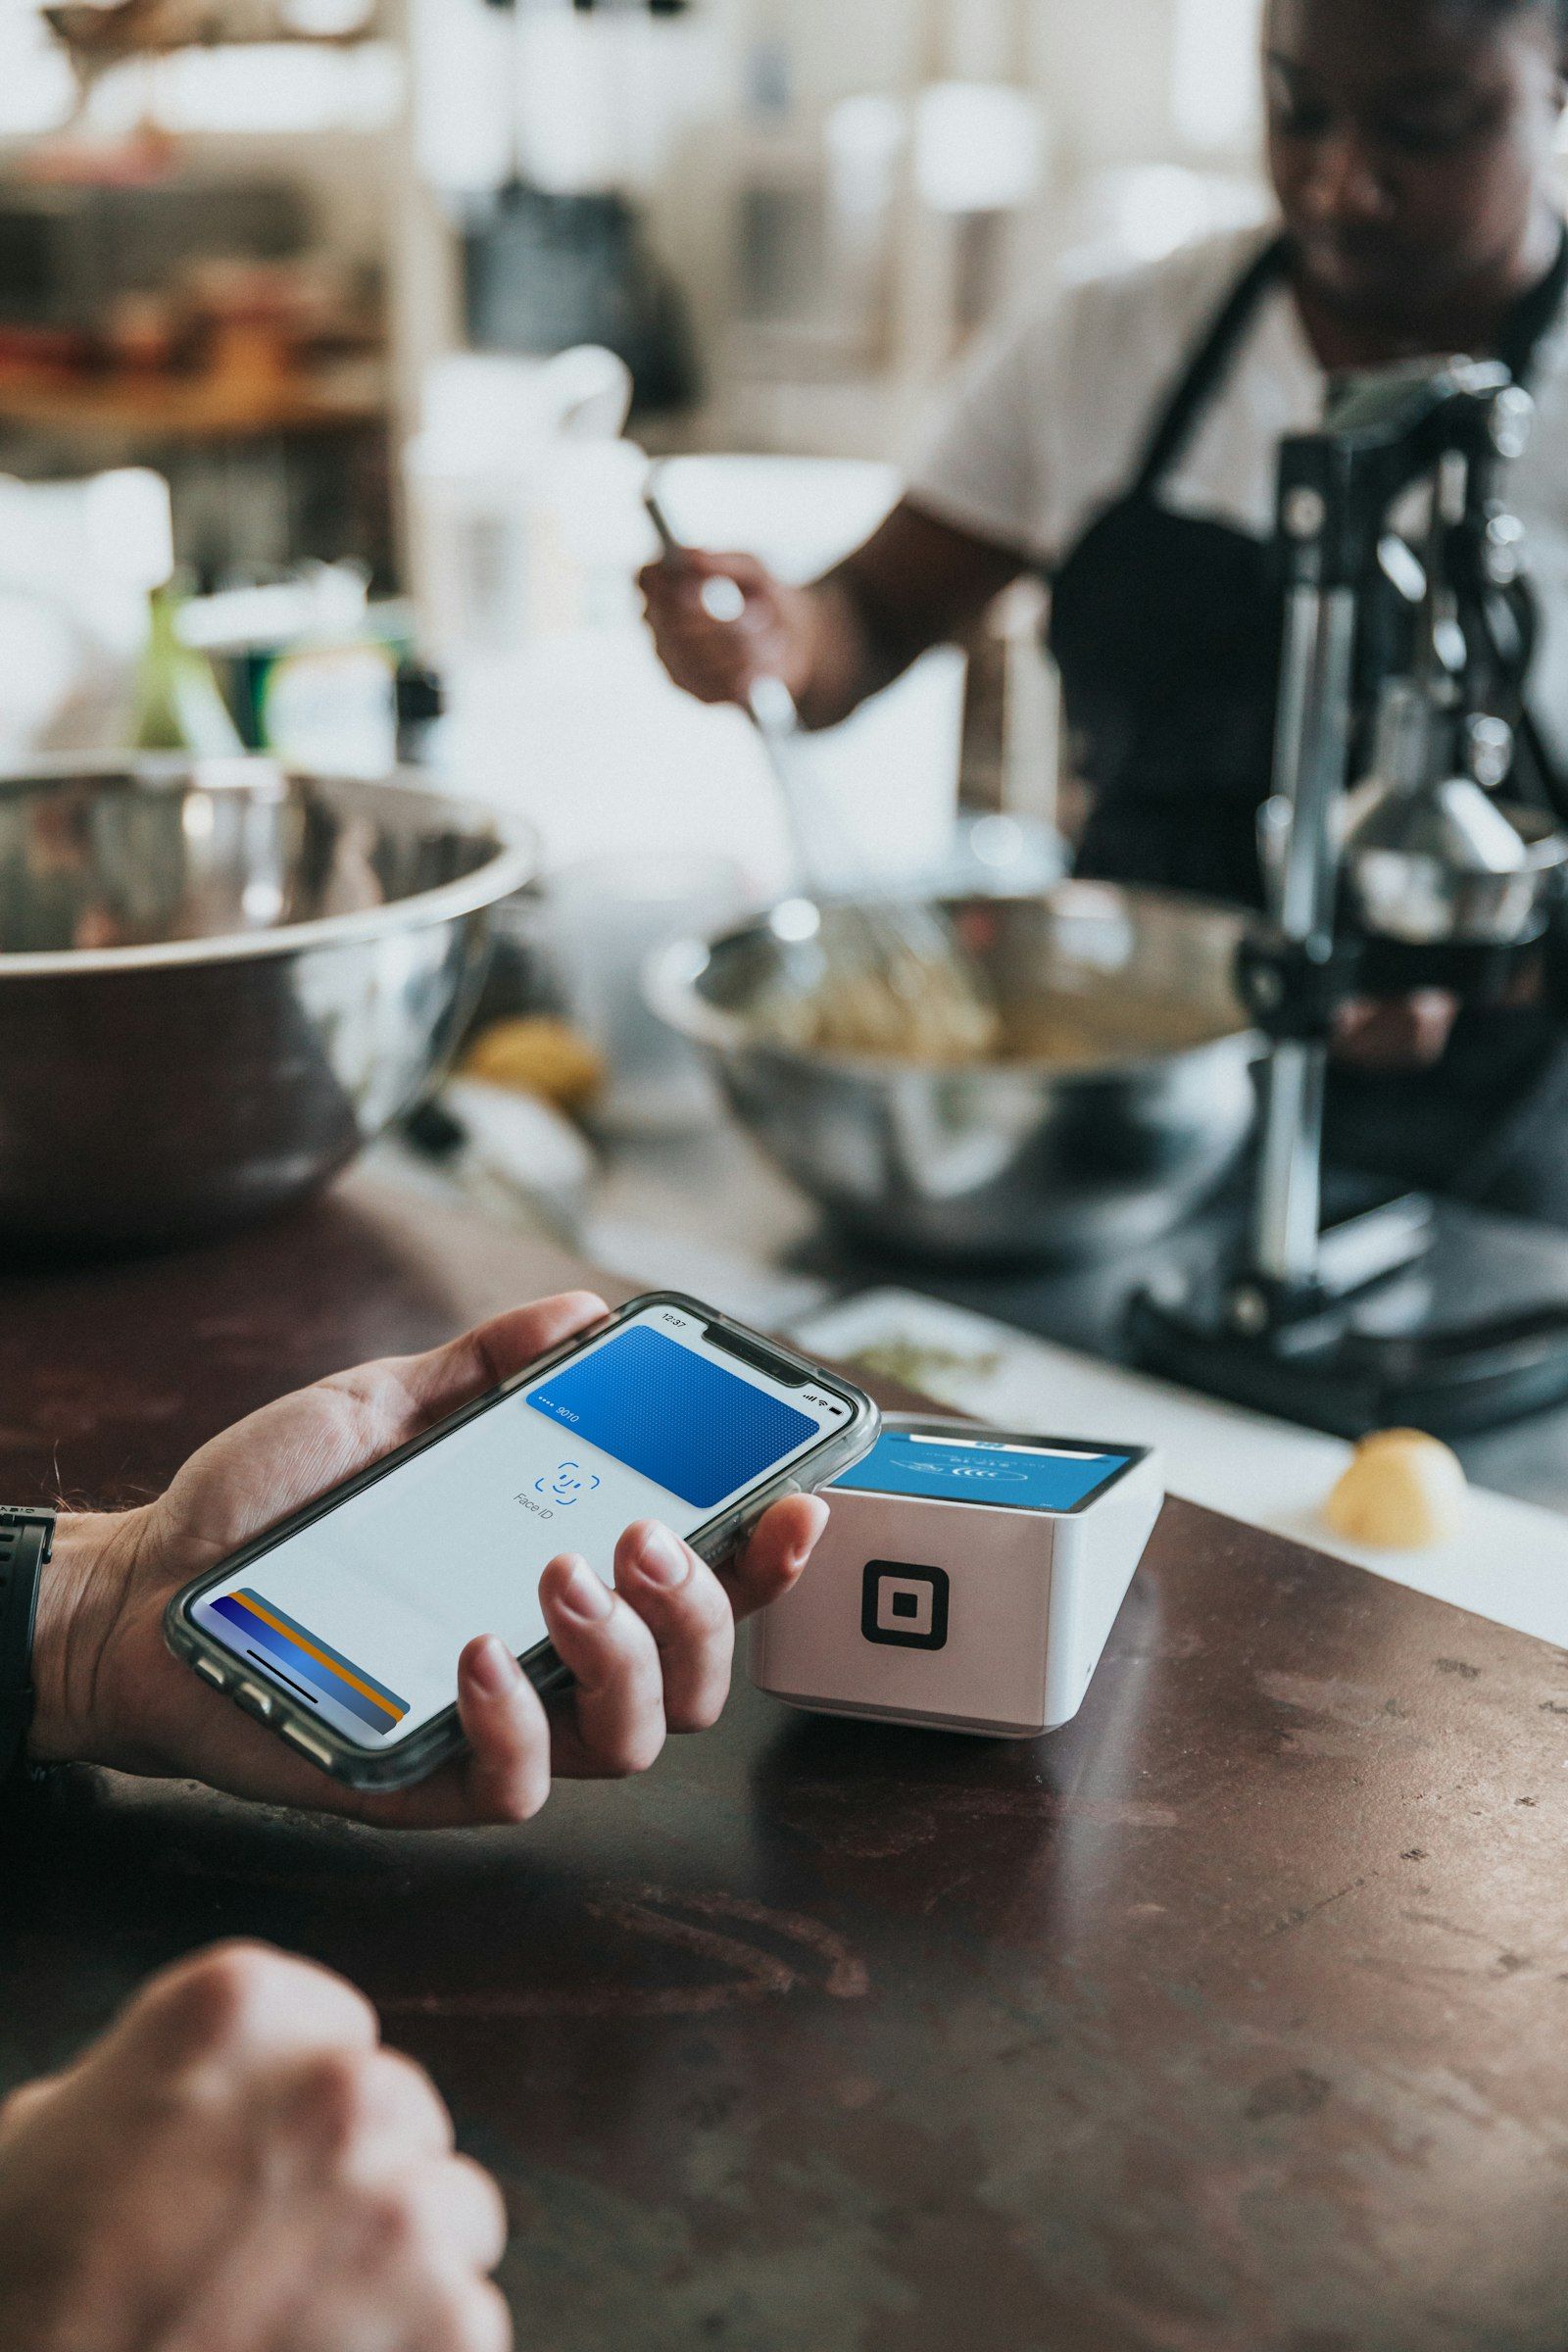
Think about the apps you use every day. You pay for rides without opening a banking app. You check out in one tap. You get paid by a marketplace straight into an in-app balance.
That is embedded finance: financial services built directly into non-financial products.
What counts as embedded finance?
- Embedded payments – accepting and sending money inside the product experience.
- Wallets and stored balances – letting users hold funds in-app.
- Embedded lending – "buy now, pay later" and working-capital offers at the point of need.
- Cards – virtual and physical cards issued by a brand for its users or employees.
- Embedded insurance – coverage offered at checkout.
Why companies are embracing it
Better user experience
Every redirect to another site or app is a chance to lose a customer. Built-in payments keep users in the flow.
New revenue streams
Payments, FX and card programs can turn a cost centre into a source of revenue.
Richer data, better decisions
When payments happen inside your product, you understand your customers' behaviour and can serve them better.
Stronger loyalty
Users who hold a balance or a card with your brand come back more often.
Why now?
Until recently, offering financial features meant years of licensing work and bank partnerships. Today, API-first infrastructure providers handle the regulated, complex pieces — compliance, settlement, risk — so product teams can focus on the experience.
Getting started
If you are considering embedded finance, ask:
- Which financial moment matters most to my users? Start there.
- Build, partner or buy? Most teams move faster on top of existing infrastructure.
- How will we handle compliance and fraud? Choose partners with these capabilities built in.
- How will this scale globally? Multi-currency support matters early.
Building on Syper
Syper gives developers the building blocks for global finance — payments, balances and real-time value movement — through one platform. If your product moves money, you can start building on Syper today.